ServicesVision Insurance
Vision Insurance in Temple Terrace
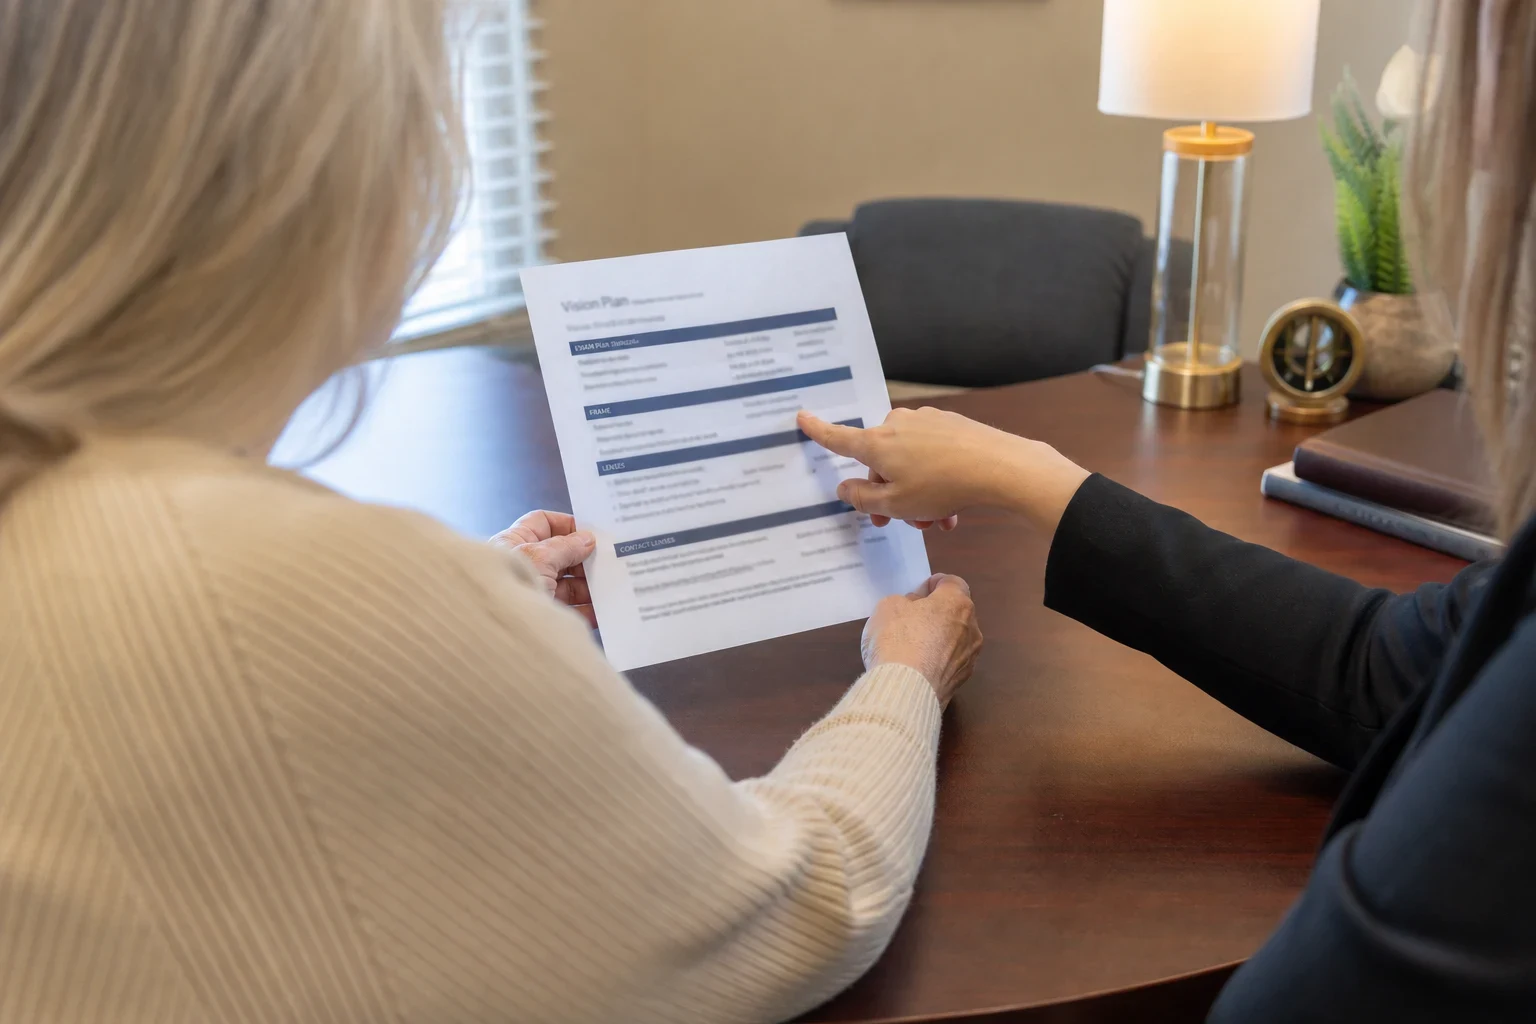
A vision plan is only as good as what it pays toward your exam, your frames and the lenses you actually wear. We lay plans from several carriers next to each other and show you the difference in plain terms before you choose one.
What a vision plan really covers
Most vision insurance pays for three things: a routine eye exam, an allowance toward frames, and a set of basic lenses or a contact lens allowance in place of glasses. The premium is usually modest. The value lives in the details, and those details differ more between carriers than most people expect.
The part that surprises clients is the lenses. A plan may cover basic plastic lenses in full, then charge a set copay for polycarbonate, high-index, anti-reflective coating or progressives. If you need thinner lenses for a stronger correction, or you spend long days on a screen, those upgrades can matter more than the frame allowance.
We walk you through each lens material and coating, what it does and what each plan charges for it. Then you can pick coverage that fits the glasses you already know you like. Health coverage for adults rarely includes routine vision care, so a separate plan often fills that gap.
What we go over with you
- Exam coverage and copays
- We check what each plan pays toward a routine eye exam, the copay you owe at the visit, and whether contact lens fittings cost extra.
- Frame allowances
- Allowances vary from plan to plan, and some are higher at certain retail chains. We show you how far each one goes and what you would pay above it.
- Lens materials explained
- Basic plastic is light and inexpensive. Polycarbonate resists impact and suits kids and active adults. High-index makes strong corrections thinner and lighter. We match each material to the copay every plan charges for it.
- Coatings and add-ons
- Anti-reflective, scratch-resistant, blue-light filtering, photochromic and polarized options are priced differently by each carrier. We list them side by side so the cost of your usual pair is clear.
- Contacts versus glasses
- Many plans give you a contact lens allowance instead of glasses in the same benefit period. We help you decide which way the benefit works best for you.
- Pairing with other coverage
- If you are also looking at dental insurance or individual health insurance, we can review them in the same conversation so the pieces fit together.
Signs a vision plan makes sense for you
You buy glasses every year or two
Regular wearers tend to get the most from a plan, since the exam and the frame allowance renew on a set schedule.
Your lenses need upgrades
A strong correction, progressives or anti-reflective coating can raise the cost of a pair quickly. Plans that discount those upgrades can make a real difference.
Your health plan leaves out adult vision
Many medical plans include pediatric vision but not routine eye care for adults. A standalone plan covers that gap.
Your kids are hard on glasses
Children often need polycarbonate lenses and replacement frames. We look for plans that handle both without much out-of-pocket cost.
You left an employer plan
Going self-employed or retiring early often means losing vision benefits you took for granted. We help you replace them.
What drives the price of vision coverage
Vision plans tend to cost less each month than medical plans, yet your bill at the optical counter comes down to how the plan is set up. A low premium paired with steep lens copays can end up costing more over the year than a plan that charges a little more but covers materials better. We add up the total for the glasses you really buy.
Size of the allowances
Bigger allowances for frames and contacts generally mean a bigger premium. It pays off only if you usually pick frames that cost more.
Copays for lens upgrades
Every plan has its own copays for polycarbonate, high-index, progressives and coatings. When you need more than one upgrade, this is the number to watch.
How often benefits renew
Frames renew every 12 months on some plans and every 24 on others. The faster cycle usually adds a little to the monthly cost.
How big the network is
A larger network means more eye doctors and optical shops to pick from. A smaller one may cost less but could leave out the provider you see today.
Who the plan covers
One adult costs less to cover than an adult plus a spouse or kids. Family pricing often comes in tiers.
How it works when you call
- 1
A short conversation
We ask how you wear your eyewear: glasses, contacts or both, your usual lens type and whether you have an eye doctor you want to keep. This can happen by phone, by video or at our office.
- 2
Plans laid side by side
We pull options from multiple carriers and compare the premium, exam copay, frame allowance and lens upgrade costs on one page. You see the trade-offs clearly, not just the monthly price.
- 3
Checking your eye doctor
We confirm whether your current optometrist or optical shop is in network for each plan you are considering.
- 4
Enrollment and next steps
Once you choose, we handle the enrollment paperwork with you and explain when your benefits start and how to use them at your first visit.
Common Questions About Vision Coverage
Isn't eye care already part of my health plan?
Usually only in part. ACA Marketplace plans cover vision care for kids, but adult eye exams and glasses are rarely included. A medical plan may pay when an eye problem comes from illness or injury, which is not the same as an annual exam and a new pair. A separate vision plan handles that routine care.
Will I be able to stay with my eye doctor?
Most of the time, yes. Before you sign up, we look up your optometrist or optical shop in each plan's network. If your doctor is not listed, we explain the fixed amount some plans pay toward out-of-network visits.
Does a vision plan pay off if all I want is an exam?
Not always. For a once-a-year exam and simple lenses, paying the bill yourself can cost about the same as the premium. If a plan won't do much for you, we say so.
What lens material should I budget for?
That comes down to your correction and how you wear your glasses. Polycarbonate works well for children and active adults, high-index suits strong corrections, and polarized or photochromic lenses help on long, bright Florida days. We find the plan with the lowest charge for the material you need.
Is there a charge to speak with you?
No. The consultation is free. Our pay comes from the company you pick, not from you, so having us look costs you nothing.
When am I allowed to enroll?
Plenty of standalone vision plans can begin outside open enrollment, though each carrier sets its own rules. Adding vision to an ACA Marketplace plan may tie you to the enrollment period. We work out which rule fits your case on the call.
See what your next pair would cost on each plan
Tell us how you wear your glasses or contacts, and we will set plans from several carriers side by side. The conversation is free and takes place by phone, video or at our office in Temple Terrace.