Health Insurance in Temple Terrace, Laid Out Plan by Plan
We help clients in Temple Terrace, Tampa and Brandon compare individual health insurance, family coverage, ACA Marketplace plans, and dental, vision and accident insurance. You see what each plan is built from (deductible, network, drug list, out-of-pocket limit) before you choose.
- Licensed independent insurance agency
- Shops 50+ insurance carriers
- No fee for the consultation
- Office, phone or video
Coverage We Help You Compare
We are a licensed independent insurance agency, and we shop 50+ insurance carriers instead of steering you toward one company. That covers individual health insurance, family health insurance and ACA Marketplace plans, plus dental insurance, vision insurance and accident insurance you can add alongside. Each plan is shown with its trade-offs written out, so the cheapest premium and the best fit are never confused.
Individual Health Insurance
Coverage for one person, with deductibles, networks and premiums from several carriers compared side by side before you choose.
Family Health Insurance
One plan for parents and children, chosen after we compare networks, family deductibles and premiums from multiple carriers with you.
ACA Marketplace Plans
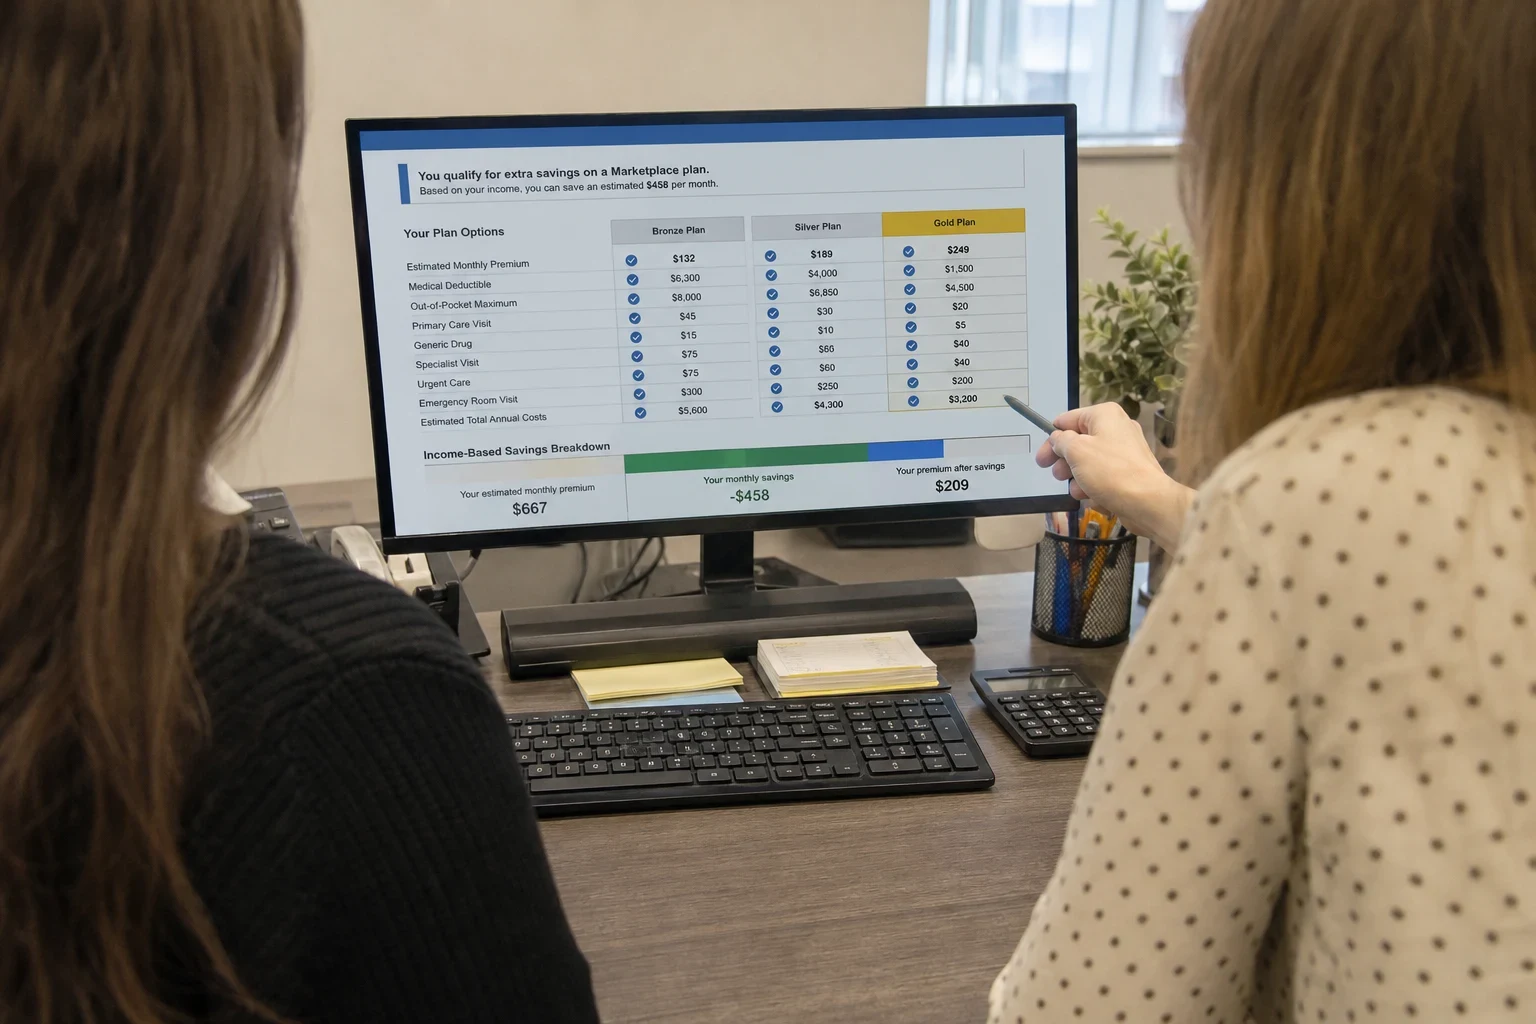
We lay out Bronze, Silver, Gold and Platinum Marketplace plans from multiple carriers so you can weigh premiums, deductibles and networks before you enroll.
Dental Insurance
We lay out dental PPO, HMO and indemnity plans next to each other so you can see waiting periods, annual maximums and networks before you choose.
Vision Insurance
Vision plans compared by what they actually pay toward exams, frames, lens materials and contacts, so you know what your next pair of glasses will cost.
Accident Insurance
Cash benefits paid to you after a covered injury, with plans from several carriers compared on one page so you can see what each one pays.
What Raises or Lowers Your Premium
We can't quote a price before we know your details, and no honest agent would. What we can do is explain the things that move a premium up or down, so the numbers we give you on the call make sense.
During the call we gather your details, get quotes from several carriers and walk through the real figures for each option. The decision to enroll is yours, and nothing is final until you say so.
- Age and tobacco use
- Individual and family plans are priced by the age of each person covered. Tobacco use often adds to the price on many plans, so we ask about it at the start.
- Metal level
- Bronze, silver, gold and platinum plans trade the monthly premium against your costs when you get care. A lower monthly price usually comes with a higher deductible, and a higher price with a lower one.
- Network style
- HMO plans tend to cost less but keep you in network and need referrals. PPO plans cost more and let you see providers outside the network. EPO plans sit between the two.
- Income and tax credits
- On ACA Marketplace plans, your expected income for the year and how many people your plan covers decide whether you receive a premium tax credit. If your income qualifies, silver plans may also include cost-sharing reductions that lower your deductible.
- Where you live
- Carriers set prices by county and rating area, and the plans on offer change from one area to the next. We only show plans that are actually sold where you live.
- Add-on coverage
- Dental, vision and accident insurance are priced on their own. Their waiting periods, annual maximums and benefit amounts all affect the cost.
Serving Temple Terrace and Nearby Communities
We work with clients throughout Temple Terrace and across the surrounding area, including Tampa, Brandon, Thonotosassa, Lutz and Carrollwood. Because the plans offered depend on your county, we confirm what is available where you live before we compare anything.
- Temple Terrace
- University
- East Lake-Orient Park
- Thonotosassa
- Mango
- Tampa
- Brandon
- Egypt Lake-Leto
- Carrollwood
- Lake Magdalene
- Lutz
You can meet with us at our office or handle everything by phone or video, whichever suits your schedule.
An Agency Built Around Careful Comparison
Private Health Insurance Temple Terrace helps people choose health coverage with a clear view of what they are buying. We spend our time on the details most people never get explained: how a deductible interacts with coinsurance, why one plan covers a medication at a lower tier than another, what a narrow network means for the specialist you already see.
Our clients include people leaving an employer plan, self-employed workers, early retirees not yet on other coverage, and families adding a newborn or a new spouse. Each starts with the same unhurried conversation, and each leaves with a plan they understand.
- License
- Licensed independent insurance agency
- Carriers
- Shops 50+ insurance carriers
What Happens When You Reach Us
Most clients finish the comparison in one conversation. If you want time to think, we pick it up whenever you are ready.
- 1
A short conversation
We ask who needs coverage, your birth dates, your expected income, and which doctors and medications matter to you. It takes about as long as a cup of coffee.
- 2
Side-by-side options
We line up plans from multiple carriers and explain each one in plain terms: premium, deductible, out-of-pocket limit, network and drug coverage. You can meet at our office, stay on the phone or talk by video.
- 3
Enrollment, done carefully
When you choose a plan, we help complete the application and double-check names, dates and income figures, since small errors can delay coverage or change a tax credit.
- 4
A check-in each year
Plans, networks and drug lists change every year. Before open enrollment we look at your coverage again and tell you if something better fits.
What Working With Us Looks Like
Every health plan is built from parts that trade against one another. We point out each one and what it will cost you.
Every plan, taken apart
Plans with close premiums can act very differently when you actually use them. We line up the deductible, coinsurance, copays and out-of-pocket maximum so you can picture both an ordinary year and a difficult one.
We start with your doctors and medications
First we ask which doctors, specialists and hospitals you want to keep and what medications you take. We check each against every plan's network and drug list, since a cheap premium is worth little if your physician isn't covered.
No push toward more coverage
For some people a bronze plan with a health savings account makes the most sense. For others who see specialists often, a gold plan costs less overall. We show you where the numbers land, and the choice stays yours.
Our review is free to you
The consultation carries no fee. The company you pick pays us, not you, so looking at several carriers adds nothing to your premium.
Support once you're enrolled
Questions arise after your card shows up: a claim that seems off, a referral requirement, a shift in income. You can call on us, and we look over your coverage again ahead of every open enrollment.
Common Questions From Our Clients
Do you charge anything to help me?
No, the consultation is free. The carrier you select pays us, so our review adds nothing to your cost. Your premium is the same as if you went to the carrier yourself.
When can I sign up for health coverage?
Individual and family plans generally open for enrollment from November 1 through January 15. Outside that period you need a qualifying life event, such as a move, a marriage, a new baby or losing other coverage, which usually gives you 60 days. Dental, vision and accident plans can often begin in any month.
Can you check whether my doctor accepts a plan?
Yes, and we do it before suggesting any plan. Tell us your doctors, specialists and the hospital you prefer, and we search each plan's directory. Networks can change mid-year, so a quick call to the office to confirm is a good idea too.
Could my existing health condition stop me from getting a plan?
No, not with ACA Marketplace plans or other ACA-compliant individual and family plans. They cannot turn you down or charge you more because of past health. Some extra coverage, like certain dental plans, may have waiting periods, and we point those out before you enroll.
How do I know if I qualify for a smaller premium?
Premium tax credits on the Marketplace are based on the income you expect next year and the number of people on your plan. During the call we estimate your likely credit and show every price both with and without it, so there are no surprises.
Should I just choose the lowest monthly premium?
Not always. A low premium often comes with a high deductible. That can work if you seldom see a doctor, and it can cost you if you take regular medications or expect surgery. We estimate what a typical year would cost you in total, not just each month.
Can I add dental or vision to my health plan?
Yes. Adult health plans frequently include little or no dental or vision, so many clients buy separate dental insurance or vision insurance. We compare those just as closely, looking at waiting periods, annual maximums and what they pay toward exams, glasses and contacts.
See Your Options Plainly
Tell us who needs a plan and what matters most to you. We will gather options from several carriers and go over the trade-offs with you at no charge.