ServicesACA Marketplace Plans
ACA Marketplace Plans in Temple Terrace
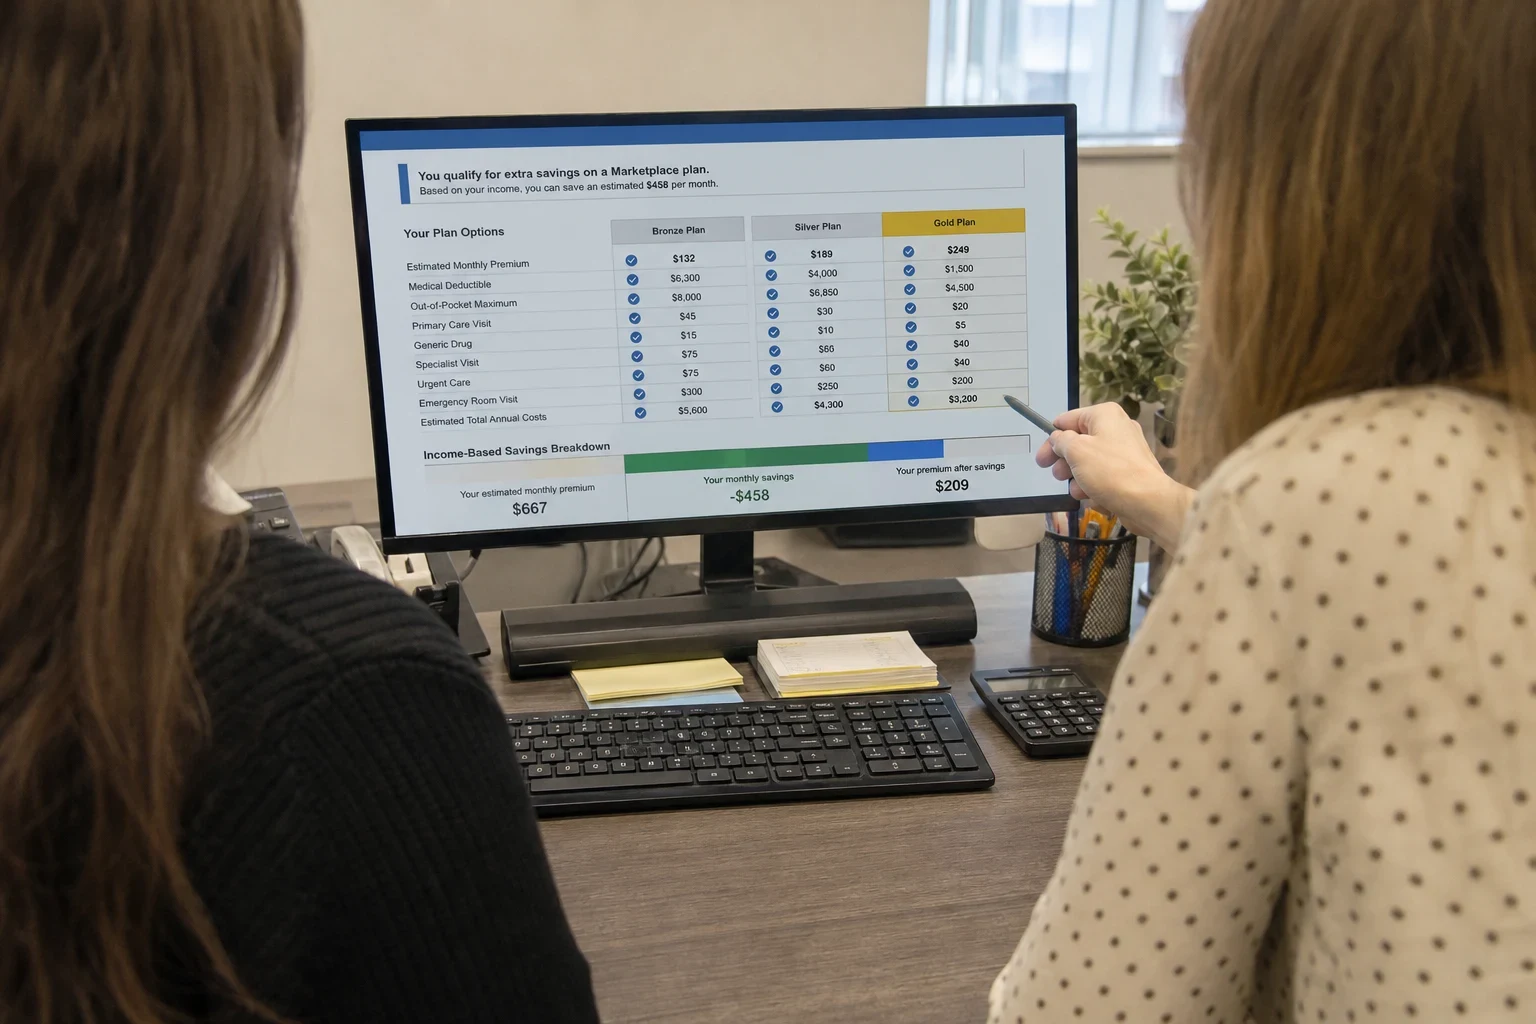
Marketplace plans are built from a handful of parts: the metal tier, the network, the deductible and the subsidy you qualify for. We explain how each part behaves, then show you side-by-side options from multiple carriers so the plan you choose fits the way you actually use coverage.
What a Marketplace Plan Is Made Of
ACA Marketplace plans are health plans for individuals and families offered on the federal exchange, the place where Floridians sign up. All of them include the same core essential benefits, so what sets them apart is how they are built: your monthly cost, your cost when you get care, and the doctors and hospitals the network includes.
Metal tiers make those trade-offs easiest to see. Bronze pairs a smaller premium with a bigger deductible. Gold and Platinum flip that around, with a higher monthly bill and lower costs when you get care. Silver lands between them and offers one benefit no other tier has, explained further down.
We go through the fine print alongside you. We set plans from several carriers next to each other, show how your income shapes the premium tax credit, and help you sign up after you decide. Our review costs you nothing, since the carrier you pick pays us rather than you.
What Our Marketplace Help Covers
A tier-by-tier walkthrough
We explain Bronze, Silver, Gold and Platinum in plain terms, using your expected doctor visits and regular medications as the yardstick. You see where each tier saves money and where it costs more.
Subsidy and tax credit estimate
Premium tax credits are based on your expected annual income and family size. We help you estimate that income carefully, since an estimate that is too low can mean paying some of the credit back at tax time.
Network checks
Two plans with the same tier can use very different networks. We check whether your current doctors and preferred hospitals are in network before you commit, across the Tampa Bay area or wherever you usually go for care.
Drug formulary review
Each carrier keeps its own list of covered medications and the tier each one sits on. We look up the ones you take so a low premium does not hide a high monthly cost at the pharmacy.
Enrollment support
Once you choose, we help you complete the application and confirm the details. If you also want dental insurance or vision insurance, we can look at those in the same conversation.
When a Marketplace Plan Is Worth a Look
You are leaving an employer plan
Losing job-based coverage usually opens a special enrollment window. That window is limited, so it helps to compare plans soon after your last day.
You are self-employed or work gig jobs
Without an employer contributing, the premium tax credit can make a meaningful difference. Your income estimate drives how much you receive.
Your income has changed
A raise, a pay cut or a new business can move your subsidy up or down. Updating your application keeps your premium accurate and avoids a surprise when you file taxes.
Your renewal letter looks different
Carriers adjust premiums, networks and formularies each year. Automatic renewal is convenient, but the plan you had may no longer be the best fit.
You are turning 26
Aging off a parent's plan is a qualifying life event. It is a good moment to choose coverage built around your own budget and habits.
Your family is growing
Marriage, a birth or an adoption can let you change plans mid-year. Our family health insurance page covers those choices in more detail.
How a Marketplace Consultation Runs
- 1
A short conversation by phone
We start with your situation: who needs coverage, your expected income, the doctors you want to keep and the medications you take. This meeting can also happen at our office or by video.
- 2
Side-by-side comparison
We line up plans from multiple carriers across the tiers that make sense for you. You see the premium after any tax credit, the deductible, the out-of-pocket maximum and the network for each.
- 3
Weighing the trade-offs
We talk through how each plan would behave in a quiet year and in a year with heavy use. There is no pressure to pick the highest tier or the lowest premium.
- 4
Enrollment and follow-up
When you are ready, we help you enroll and confirm your start date. If your income or family changes during the year, call us and we will help you update your application.
What Shapes Your Marketplace Premium
Marketplace prices are set by carriers and then reduced by any tax credit you qualify for, so two neighbors can pay very different amounts for the same plan. The consultation itself carries no fee. These are the parts that move what you pay.
- Income and family size
- The premium tax credit is tied to your expected income compared with the federal poverty level for your family size. Lower income generally means a larger credit.
- Metal tier
- Higher tiers carry higher premiums and lower costs when you use care. The right choice depends on how often you expect to see a doctor or fill medications.
- Silver plan cost-sharing reductions
- If your income falls within a certain range, Silver plans come with extra savings that lower your deductible and copays. These reductions are only available on Silver, which can make it the strongest value for some clients.
- Age and tobacco use
- Premiums rise with age, and carriers in Florida may charge more for tobacco users. Your tax credit can offset some of that difference.
- Network design
- HMO-style plans with narrower networks often cost less than broader PPO-style plans. The savings only matter if your doctors are included.
Marketplace Plan Questions We Hear
Something not covered here? (813) 212-7908
What are the dates to sign up for a Marketplace plan?
Florida runs through the federal exchange, which opens enrollment every fall and closes it in mid-January. During the rest of the year you need a qualifying life event, such as moving, marrying, having a child or losing other coverage. You typically get 60 days after the event to enroll.
Will I pay more by enrolling through you?
No. The Marketplace premium is identical whether you enroll on your own or with us. We are paid by the carrier you choose, so the consultation and the enrollment are both free to you.
Should I pick Bronze or Gold?
Start with how much care you used last year. If you rarely see a doctor, Bronze and its lower premium often wins. If you visit specialists often or fill prescriptions every month, Gold and its smaller deductible may cost less over the year. We run both scenarios with you.
What if my real income differs from what I estimated?
Your tax credit is reconciled on your federal tax return. If you earn more than expected, you may owe some of it back; if you earn less, you may get more. Updating your application when things change keeps that gap small.
Will I be able to keep seeing my doctor?
Often you can, but it depends on the carrier and the network of each plan. We check your doctors before you enroll, not after. If one doctor matters most, tell us up front and we will shape the options around them.
How does a Marketplace plan differ from individual health insurance?
A Marketplace plan is one kind of individual coverage, and it is the only kind that can include a premium tax credit. Some clients are better served by plans sold outside the exchange, which we cover on our individual health insurance page.
Compare Your Marketplace Plans Before You Enroll
A short call is enough to see how the tiers, networks and subsidies line up for you. The consultation is free, and you decide only once you have seen the options side by side.